Buying a Jonesboro Home When You're Self-Employed
Can you buy a home in Jonesboro if you are self-employed?
Yes. Self-employed Jonesboro buyers can qualify, but lenders usually want two years of tax returns and look at net income after write-offs. Prepare your paperwork before you shop.
If you run your own business, work as a contractor, or farm, you already know your income does not arrive on a single paycheck. A mortgage lender sees that differently than you do, and it catches a lot of Jonesboro buyers off guard.
At NEA Realtor Group, Trenton Hoggard and Tim Ray work with self-employed buyers across Northeast Arkansas, and the ones who do best start on paperwork before they start on touring homes. The goal of this guide is to show you what lenders look for and what to do in the months before you write an offer.
Rates add pressure right now. Freddie Mac's weekly survey put the 30-year fixed rate at 7.28% on October 1, 2026, up from 7.03% the week before. A higher rate leaves less room in the budget, which makes a clean, well-documented income file more important.
How Lenders Look at Self-Employed Income
A salaried buyer hands over a pay stub. A self-employed buyer hands over tax returns, and the lender works from the bottom line of those returns, not from what your business brought in.
That is the part that surprises people. Every legitimate write-off lowers your taxable income, and lower taxable income can mean a smaller loan.
- You may bring in a strong year, then write off equipment, a truck, supplies, and home office costs so your tax bill is small.
- The lender generally uses the net figure on your return, with limited adjustments for certain non-cash items. Ask any lender how they treat items like depreciation.
- The same write-offs that save you money in April can shrink the monthly payment you qualify for in October.
Neither approach is wrong. Just know that buying a home is a moment when reported income matters, so it is worth talking to your tax professional before the year the purchase is planned.
The Paperwork to Gather Before You Talk to a Lender
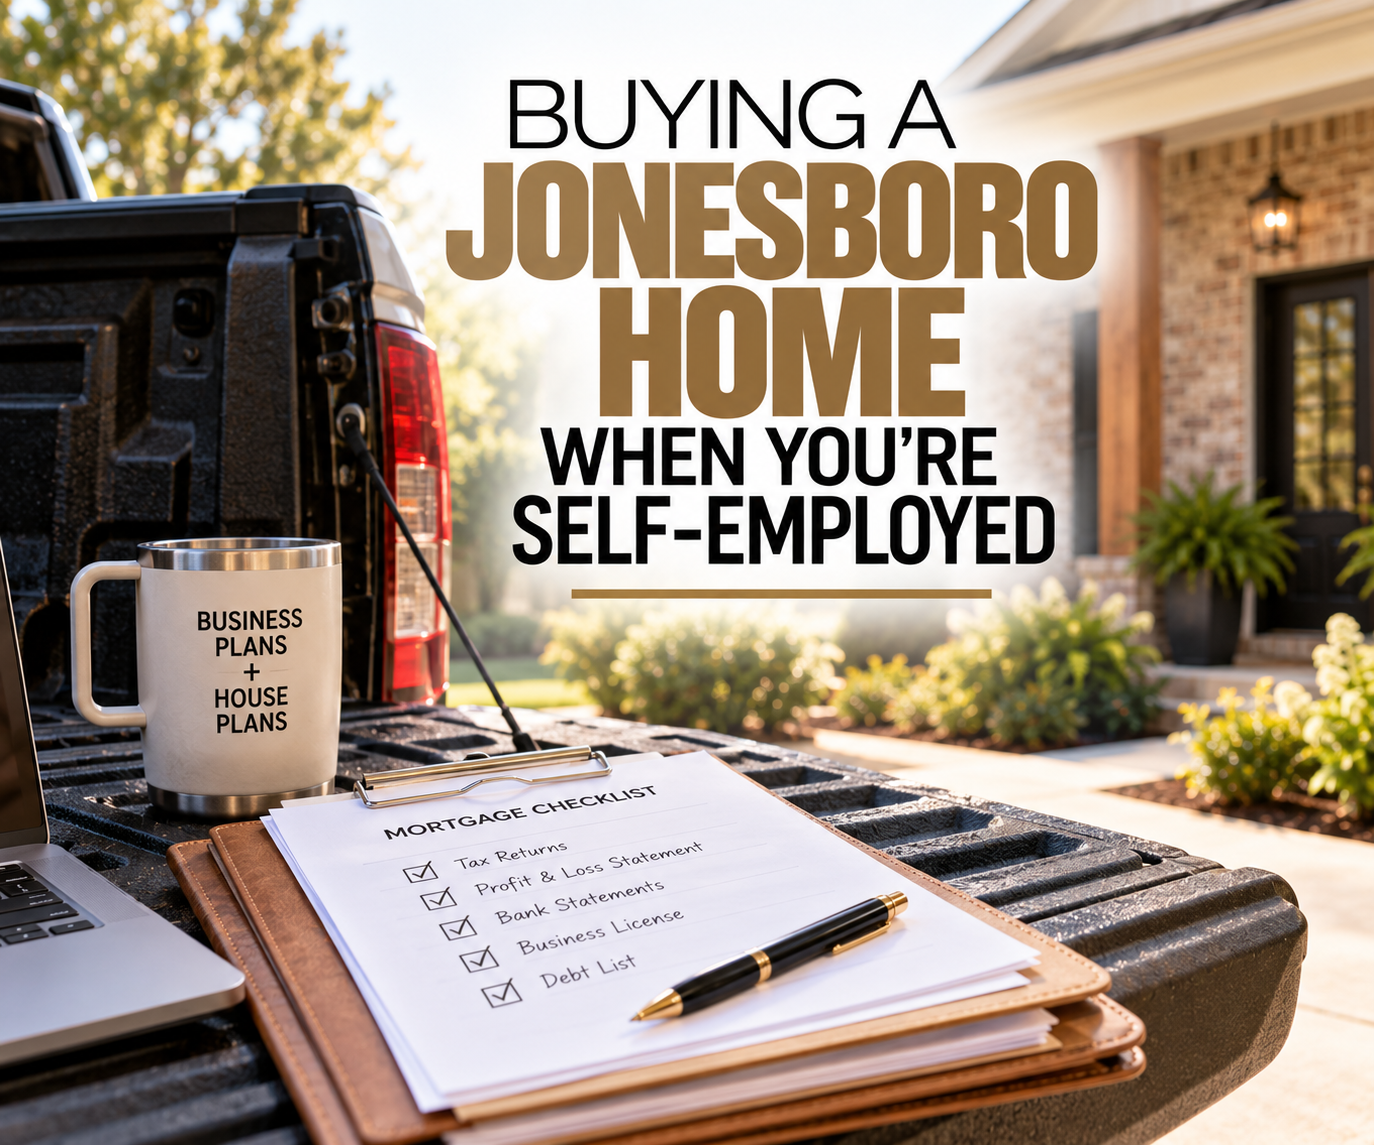
Every lender has its own checklist, but these items come up in nearly every self-employed file. Having them in one folder saves days.
- Two years of complete personal federal tax returns, with all schedules.
- Two years of business tax returns if your business files separately, such as an LLC taxed as a partnership or an S corporation.
- A year-to-date profit and loss statement, often prepared by your accountant or bookkeeper.
- Recent business and personal bank statements.
- Proof that the business is active, such as a business license or a letter from your accountant.
- A list of monthly debts, including business loans or equipment payments that are in your name.
Lenders also confirm your returns with the IRS using a signed request form, so make sure your filed returns match the copies you hand over.
The Two-Year Rule and Its Exceptions
The common expectation is a two-year history of self-employment income. Fannie Mae's Selling Guide describes a two-year earnings history as the general rule, and it also allows a shorter history when the most recent returns show a full 12 months of self-employment income and your prior work in the same or a similar field supports it.
FHA loans follow a similar idea. The FHA Single Family Housing Policy Handbook 4000.1 treats borrowers with a 25 percent or greater ownership interest in a business as self-employed. If you have been self-employed for one to two years, the income can count only if you worked in the same line of work for at least two years beforehand.
Guidelines change and each lender applies them a little differently, so treat this as a map and not a promise. A lender can tell you how your own situation reads.
If you recently left a job to start your own business
This is the most common timing problem. If you left a salaried job in the same field less than two years ago, ask a lender early whether your prior work history helps your file. If you are thinking about going out on your own, buying first and changing jobs second can make qualifying easier.
What Happens If Your Income Dipped
Lenders look at the trend. Income that is steady or growing is easier to approve than income that dropped last year, even if the two-year average looks fine.
Under FHA rules, a decline of more than 20 percent in effective income over the analysis period sends the file to manual underwriting, and the lender may use the lower of the two-year average or the one-year average. That can pull your qualifying income down.
If you had a one-time reason for a down year, such as a major repair, an injury, or a large one-time purchase for the business, write it down and give it to the lender with documentation. A short, factual letter of explanation can help an underwriter understand the numbers.
How to Strengthen Your File Before You Apply
The months before you apply matter more than most buyers expect. Here is what we tell self-employed clients to focus on.
- Keep business and personal money separate. A dedicated business account makes your deposits easy to trace.
- Avoid large, unexplained deposits. Underwriters ask about them, and every question slows the file.
- Do not open new credit. A new truck loan or credit card in the middle of the process can change your debt picture.
- Pay down personal debt where you can. Lower monthly obligations leave more room in the payment you qualify for.
- File your taxes on time. An extension or an unfiled return delays the process.
- Ask your accountant about timing. If a major purchase or write-off is on the horizon, find out how it affects the return a lender will see.
If a co-borrower could help your file, our guide on using a co-borrower to buy a home in Jonesboro explains how that works and where it does not.
Alternative Documentation Loans: The Trade-Offs
Some lenders offer loans that qualify you on bank statements or other documents instead of tax returns. These are often called bank statement loans or non-QM loans.
They can help when your write-offs lower your tax return income below what you actually earn. They also tend to come with higher rates, larger down payments, or extra fees than a conventional loan. Ask for the full cost side by side, including rate, fees, and down payment, before you decide.
We cannot recommend a specific lender, and it is smart to speak with more than one so you can compare how each reads your income.
Writing the Offer in Jonesboro as a Self-Employed Buyer
Once your pre-approval is in hand, the process looks like any other Jonesboro purchase, with a few local details worth knowing.
- Make sure the pre-approval is fully underwritten on your income. A letter based only on what you told a lender carries less weight with sellers than one where your documents have been reviewed.
- Earnest money is the exception here, not the rule. In Northeast Arkansas, the majority of deals do not include earnest money at all. When buyers do put money down, $1,000 is the most common figure, with higher amounts typically reserved for luxury transactions.
- Plan for a home inspection. A standard single-family inspection in our area typically runs $500 to $1,000, with larger homes and add-on services costing more.
- Expect a termite letter. In Arkansas, plan on a termite letter for almost any financed purchase in Jonesboro. The main exceptions are an in-house bank loan or paying cash.
- Budget for cash to close. Our breakdown of what Jonesboro buyers actually wire at closing shows where the money goes.
Because Jonesboro has lower sales volume than a metro market, comparable sales for pricing can reach back 90 to 180 days. That helps explain why a precise price opinion from a local agent is worth getting before you offer. You can also watch national conditions through NAR's research and statistics and track Jonesboro trends on Redfin's Jonesboro market page.
Frequently Asked Questions
Q: How long do I need to be self-employed to get a mortgage in Jonesboro?
The common expectation is two years, but some loan programs allow a shorter history if your recent returns show a full year of self-employment income and you have prior experience in the same field. A lender can tell you how your history reads under their guidelines.
Q: Will my tax write-offs hurt my chances of getting approved?
They can. Lenders generally qualify you on the net income shown on your tax returns, so large write-offs lower the income they can count. Talk with your accountant before the year you plan to buy.
Q: Can I use a bank statement loan instead of tax returns?
Some lenders offer them, and they can help when write-offs hide your real cash flow. They often cost more than a conventional loan, so compare the full terms before you choose.
Q: How early should I start preparing if I want to buy in Jonesboro?
Ideally three to six months before you plan to make offers. That gives you time to gather returns, clean up your accounts, and fix any problems a lender flags.
Ready to Get Your Self-Employed Buyer File in Order?
Before you start touring homes, we can walk through your timeline and budget, point you to the right questions for lenders, and help you set a price range that fits how you actually earn. For perspective, NEA Realtor Group has earned 5-star reviews and is the #1 real estate team in the Northeast Arkansas MLS by production.
Ready to Take the Next Step?
Thinking about buying a Jonesboro home while running your own business? Trenton Hoggard and Tim Ray will help you plan the timeline, the budget, and the offer.
Connect with NEA Realtor Group