Buying a Duplex in Jonesboro and Living in One Side
Can you buy a duplex in Jonesboro and live in one side?
Yes. In Jonesboro, you can buy a duplex with an owner-occupied loan, live in one unit, and rent the other. Financing, rent income, and inspection details decide whether the numbers work.
A duplex looks like a simple idea: live in one side, rent the other, and let the second unit help cover the payment. In Jonesboro and across Northeast Arkansas, plenty of buyers are asking whether it really works.
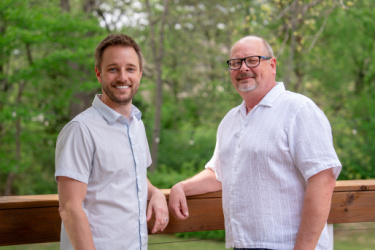
It can. But it's a different purchase than a regular house, and the differences show up in the loan, the inspection, and the offer. Trenton Hoggard and Tim Ray with NEA Realtor Group walk buyers through these deals, and here's what we want you to know before you write one.
This guide is for buyers who plan to actually live in the property. If you're buying purely as an investor, our investor services page is a better starting point. If you're new to the process overall, start with our page on buying a home.
Why a Duplex Changes the Math
With a regular house, the payment is the payment. With a duplex, part of your monthly cost can be offset by rent from the other unit, and lenders may count some of that rent when they qualify you.
That's the appeal. It's also where buyers get into trouble, because rent on paper and rent in your bank account are two different things.
Rates matter here too. As of September 24, 2026, Freddie Mac reported the average 30-year fixed rate at 7.03%, up from 6.95% the week before and 6.30% a year ago. At those levels, every dollar of predictable rent helps, but you can't build the whole plan around it.
Housing supply is loosening nationally. The National Association of Realtors reported months of supply at 4.9 for August 2026, the highest in more than a decade. Duplexes are a small slice of any local market, so waiting for the perfect one can take longer than waiting for a single-family home.
How Owner-Occupied Duplex Loans Work
The key word is owner-occupied. When you plan to live in one unit, you can generally use loan programs built for primary residences, which usually carry better terms than investor loans.
Here's how the common options line up for a two-unit property:
- FHA: Allows one- to four-unit primary residences with a low down payment. Rent from the unit you won't occupy can be counted as income, but lenders apply a haircut. HUD's FHA Mortgagee Letter 2023-17 describes using 75 percent of the lesser of the appraiser's fair market rent or the actual lease rent when there's limited rental history.
- Conventional: Fannie Mae and Freddie Mac programs allow owner-occupied two- to four-unit purchases, and the Fannie Mae Selling Guide has allowed down payments as low as 5 percent on multi-unit primary residences since late 2023. Guidelines change, so confirm current terms with your lender.
- VA: If you're eligible, a VA loan can be used for a property with up to four units when you live in one of them. We cover the basics in our VA loan post.
- USDA: These loans are popular across rural NEA, but they're generally built for single-family homes, so they typically aren't a fit for a duplex.
Three- and four-unit properties add another layer: FHA requires reserves of three months of the full payment after closing, and the property has to pass a self-sufficiency test. A duplex sidesteps that test, which is one reason two-unit buildings are the sweet spot for first-time owner-occupants.
We don't recommend specific lenders, but we can tell you which questions to ask, and we encourage you to compare more than one lender before you commit.
What Lenders Look At Before They Count the Rent
Lenders don't take your word on what the other unit will bring in. Expect them to look at:
- The appraiser's rent estimate for the unit you won't live in
- A signed lease, if the unit is already occupied
- Your own income and debt, since rent usually can't carry the whole qualification
- Reserves in the bank after closing
- A vacancy allowance, meaning they assume the unit won't be rented every month
First-time buyers should ask one more question: does my lender count projected rent if the unit is vacant at closing? Some programs allow it with conditions, and some don't. Get that answer before you fall in love with a specific building.
Inspection Matters More on Two Units
A duplex is two homes sharing walls, and often a roof, a foundation, and a set of utilities. Problems on one side don't stay on one side.
In Northeast Arkansas, a standard home inspection typically runs $500 to $1,000, and a duplex will usually land toward the higher end because there are two kitchens, two sets of systems, and more to look at. Add-ons like a sewer scope or crawlspace assessment can push that higher.
Here's what we tell buyers to focus on:
- Separate meters: Confirm whether electric, water, and gas are metered separately. If they aren't, you may be paying utilities for your tenant.
- Shared systems: Look at whether the units share a water heater, a furnace, or a sewer line. Shared systems complicate repairs and tenant conversations.
- The party wall: The wall between the units affects sound and fire separation. Have your inspector look at it closely.
- Roof and foundation: These are the expensive items, and they belong to both units. If the building is older or needs work, our fixer-upper guide covers how to think about repair costs and financing.
In Arkansas, plan on a termite letter for almost any financed purchase in Jonesboro. The main exceptions are an in-house bank loan or paying cash.
Running the Numbers Like a Landlord
This is where owner-occupants often underestimate the job. You'll be the landlord, and landlords carry costs a typical homeowner never thinks about.
Build a monthly budget that includes:
- Principal, interest, property taxes, and insurance on the whole building
- A landlord or multi-unit insurance policy, which can cost more than a standard homeowner policy
- Repairs and maintenance for both units, not just yours
- Vacancy: some months the second unit will sit empty
- Lawn care, trash, and any utilities you cover
A useful test: if the second unit sat empty for three months, could you still make the payment comfortably? If the answer is no, the deal is too tight.
Also ask for the rent history on the second unit if it's occupied. Ask what the current tenant pays, when the lease ends, and whether the rent is at market. A tenant paying well below market can be a hidden cost, and a lease that ends the week after closing changes your plan.
The Landlord Side of Arkansas Law
Owning a duplex means following Arkansas landlord-tenant rules for the unit you rent out. Two basics worth knowing before you buy:
- Security deposits generally have to be returned within 60 days after the tenancy ends, under Ark. Code Ann. § 18-16-305.
- A month-to-month tenancy generally requires 30 days of written notice to end, under Ark. Code Ann. § 18-17-704.
Screen every applicant with the same written criteria, and apply them the same way every time. Fair housing rules apply to how you choose and treat tenants, and consistency is the simplest protection.
We're real estate agents, not attorneys, so have a Jonesboro real estate attorney review your lease form and the rules before you take possession.
Writing the Offer on a Duplex
Offers on duplexes aren't much different from offers on houses, but a few details deserve attention:
- Earnest money: In Northeast Arkansas, the majority of deals don't include earnest money at all. When buyers do put earnest money down, $1,000 is the most common figure.
- Tenant documents: Ask for copies of leases, deposit amounts, and rent payment history as part of your due diligence.
- Tenant status at closing: Decide whether you want the second unit delivered occupied or vacant, and write it into the contract.
- Appraisal: Multi-unit appraisals can be harder because there are fewer comparable sales. In Jonesboro, comps may pull from the last 90 to 180 days, and sometimes further back for duplexes.
If the appraisal comes in short, you still have options: renegotiate, bring more cash, or walk away under your contingency. That's a good reason to keep your inspection and financing contingencies in place.
Is a Duplex the Right Move for You?
A duplex can be a smart way to lower your housing cost, but it isn't right for everyone. It tends to work best for buyers who:
- Plan to stay in the home for a few years at least
- Are comfortable being a landlord, including the occasional late-night maintenance call
- Have savings beyond the down payment for repairs and vacancies
- Want to build equity while someone else helps with the payment
If you'd rather not share walls or manage a tenant, a single-family home may fit better. We're happy to talk through either path with no pressure.
Frequently Asked Questions
Q: Do I have to live in the duplex to get an owner-occupied loan?
Yes. Owner-occupied loan programs generally require you to live in one unit as your primary residence, usually for at least a year. If you plan to rent both sides from day one, you'd be looking at an investment property loan instead.
Q: Can I use the rent from the other unit to qualify?
Often, yes, but with limits. Lenders typically count only a portion of the projected or documented rent, and they may still want your own income to carry most of the qualification. Ask your lender how they treat rent on your specific loan type.
Q: Is a duplex harder to sell later?
It can take longer, because the buyer pool includes both owner-occupants and investors and the total number of duplexes is smaller. The upside is that both groups can be interested, which sometimes widens your options when you're ready to sell.
For perspective, NEA Realtor Group carries 5-star reviews and stands as the number one real estate team in the Northeast Arkansas MLS by production, so we've helped plenty of buyers work through multi-unit decisions.
Thinking About Buying a Duplex in Jonesboro?
Trenton Hoggard and Tim Ray with NEA Realtor Group can help you compare duplexes, run the numbers, and write an offer that protects you.
Connect with NEA Realtor Group